Bank Stress Testing
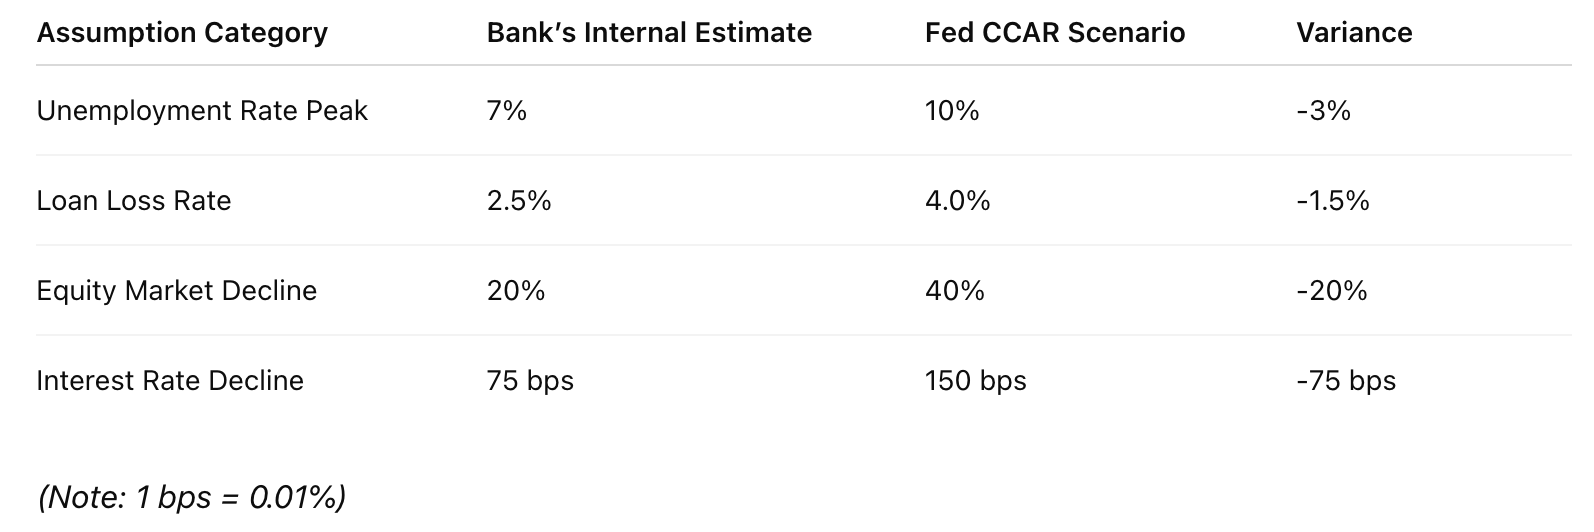
EY conducted a review comparing Eastern Capital Bank’s internal risk model assumptions to Federal Reserve CCAR baseline scenarios. The team identified several discrepancies, shown in the exhibit below. Based on this data, which assumptions should Eastern Capital Bank focus on aligning more closely with Federal Reserve expectations, and why?
Case Exhibit
Key Priorities for Review:
- Equity Market Decline (Variance: -20%): Largest gap; underestimating market shock could lead to underreported capital needs.
- Loan Loss Rate (Variance: -1.5%): Critical credit risk factor; significant impact on loss projections under stress.
Secondary Priorities:
- Unemployment Rate Peak (-3%): Material but slightly lower risk impact.
- Interest Rate Decline (-75 bps): Important but comparatively less sensitive than loan losses and equity markets.
Main Takeaway: Eastern Capital Bank’s most urgent priority is to align its assumptions for equity market decline and loan loss rates, as these represent the largest gaps with the highest financial impact in a stressed scenario. The next step should be to quantify how adjusting those assumptions would affect capital ratio projections, confirming whether capital adequacy would remain sufficient under regulatory scenarios.